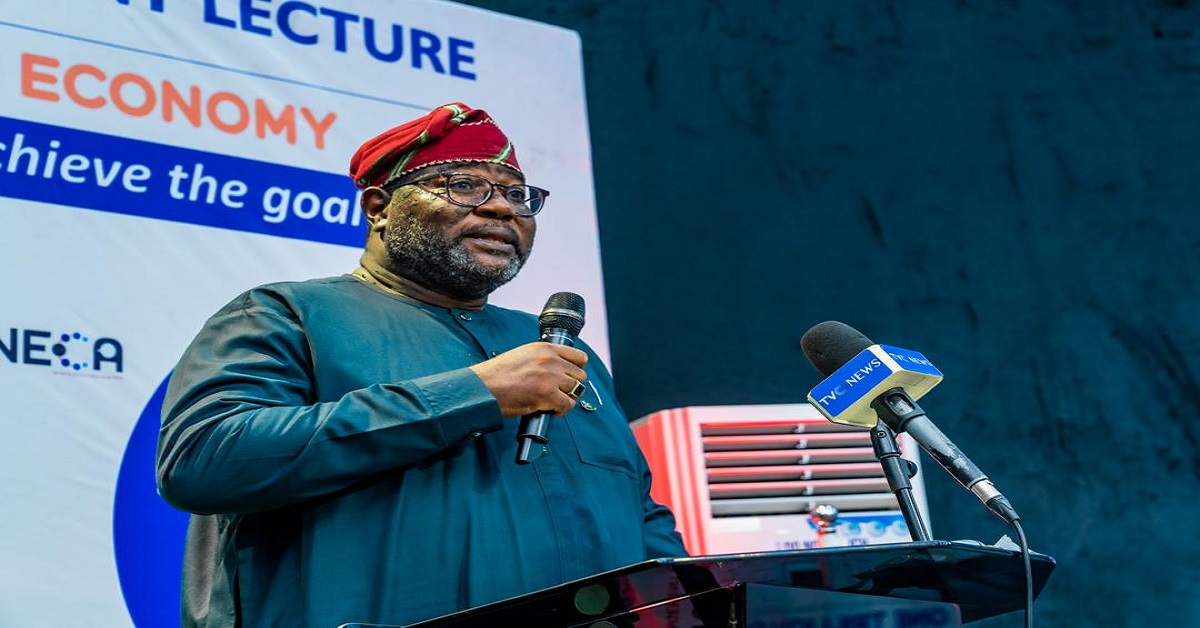
President of the Chartered Institute of Directors Nigeria (CIoD), Adetunji Oyebanji, has revealed that Nigeria requires an annual compound economic growth rate of 28.02% to hit its $1 trillion GDP target by 2030, up from an estimated $290.79 billion in 2025.
Oyebanji spoke in Lagos during the 42nd Dr. Michael Omolayole Management Lecture, organized by the AIESEC Alumni Association under the theme “One Trillion Dollar Economy: What It Will Take Nigeria to Achieve It.”
The annual lecture gathers senior executives, policymakers, and industry leaders to discuss key economic development imperatives in honor of management icon Dr. Michael Omolayole.
Oyebanji said the required growth rate was highly ambitious and had no historical precedent for an economy of Nigeria’s current size, stressing that the target could not be achieved through incremental improvements or business-as-usual policies.
“The ambition cannot be achieved through incremental improvement or business-as-usual policies. There is a need for sustained acceleration in economic growth, structural transformation and investment,” he said.
Oyebanji identified power shortages, infrastructure deficits, and inefficiencies in the oil sector and foreign exchange volatility as major structural constraints limiting Nigeria’s economic expansion.
He also cited the country’s low tax-to-GDP ratio, insecurity, policy inconsistency, and human capital deficits as factors affecting economic growth.
According to him, Nigeria must move beyond dependence on its abundant economic resources by strengthening institutions and ensuring consistency in government policies.
He said the country needed to create an environment capable of attracting private-sector investment and supporting industrial expansion.
“Economic potential alone does not guarantee economic size. It will be achieved through disciplined governance, effective institutions, consistent policies, and a shared commitment to national development,” Oyebanji said.
The CIoD president noted that recent reforms in monetary policy, tax administration and the petroleum sector were contributing to improved economic conditions, greater investment certainty and fiscal sustainability.
He said reforms by the Central Bank of Nigeria had contributed to the moderation of inflation, improved stability in the foreign exchange market and stronger investor confidence.
Oyebanji added that tax administration reforms could strengthen domestic revenue mobilisation and reduce Nigeria’s dependence on oil revenues, while petroleum sector reforms could improve transparency, investment certainty and production capacity.
He identified oil and gas, agriculture and agro-processing, manufacturing, technology and the digital economy as key sectors capable of driving economic expansion.
Other sectors he highlighted included infrastructure, solid minerals, services and the creative industry.
Oyebanji outlined 10 strategic pillars for achieving the transformation, including macroeconomic stability, institutional strengthening, policy consistency, regulatory certainty, infrastructure development, domestic revenue mobilisation, private-sector and investment promotion, industrialisation and economic diversification.
He also emphasised human capital development, technological and digital transformation, good governance, transparency and the rule of law.
The CIoD president urged the government to accelerate investment across productive sectors, strengthen infrastructure, maintain fiscal and monetary discipline and expand Nigeria’s export capacity.
He also called for improved industrial competitiveness, deeper development of the digital economy and stronger domestic revenue mobilisation.
Oyebanji urged the government to maintain consistency in its policies to restore and sustain investor confidence, while stressing that the success of the $1 trillion ambition should ultimately be meas…